September RAPI gains led by smaller, higher-quality round diamonds
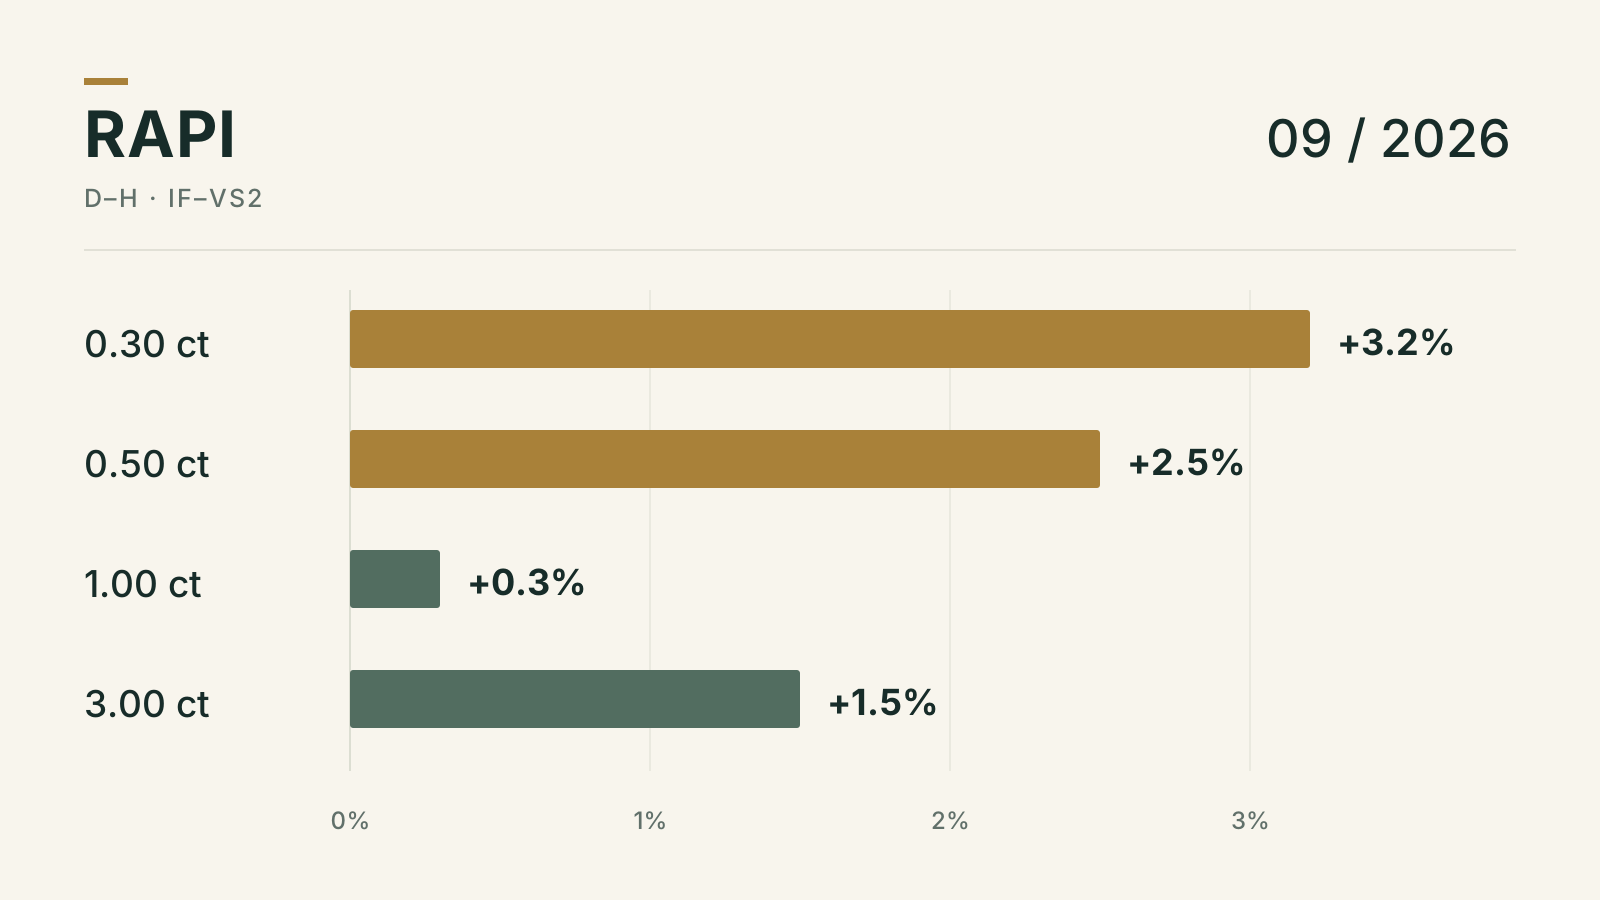 Original chart: Jewel Daily · Data: Rapaport (2026-10-06)
Rapaport's October 6 release shows the 0.30- and 0.50-carat indices outpacing the 1- and 3-carat categories in September. RAPI measures asking prices for specified grades of round diamonds; it does not measure completed transactions or the entire diamond market.
Four categories rose in September
Rapaport reviewed September's diamond market in a release dated October 6, 2026. Monthly RAPI increases were 3.2% for 0.30-carat diamonds, 2.5% for 0.50-carat stones, 0.3% for 1-carat goods and 1.5% for the 3-carat category. The 1-carat index rose for a second consecutive month, while most of the 3-carat gain occurred in the second half of September.
October 6 is the publication date; September is the period covered by the monthly figures. The 0.30- and 0.50-carat indices were up 15.1% and 5.8%, respectively, for the year to date. Those cumulative changes cover a different period from September's monthly gains.
What RAPI measures
The RAPI figures cover round diamonds in D–H colours and IF–VS2 clarities. Rapaport's methodology further specifies GIA-graded stones meeting RapSpec-A3 or better. It averages the asking prices of the lowest-priced 10% of diamonds within each of 25 quality categories offered on Rapaport Trade.
The index therefore records movements in asking prices for goods meeting these criteria. It is not a record of completed sales or a single price for every diamond shape, quality and weight. Nor does it directly measure retail price changes for finished jewellery.
Recovery varies by quality
Rapaport linked the increase to reduced supply and improving demand. It said round diamonds continued to outperform fancy shapes after a sharper earlier reduction in round production. US retailers were actively buying rounds, with demand continuing to recover for 1- to 2-carat, F–I, VS2–SI2 goods. That demand description covers a different range from the RAPI sample.
Smaller diamonds in lower qualities still faced competition from laboratory-grown stones. The Jewellery & Gem World show in Hong Kong also presented a mixed picture: demand for diamonds of 2 carats and above was solid, while smaller, lower-quality goods remained difficult to sell. Rising indices in four categories do not establish a simultaneous recovery across every market and product segment.
Editorial observation
The figures are useful for examining differences between categories. Comparisons need to retain the carat group, quality range and measurement period. Gains for smaller stones in higher qualities cannot be extended to all small diamonds or to jewellery retail prices as a whole.
Related articles
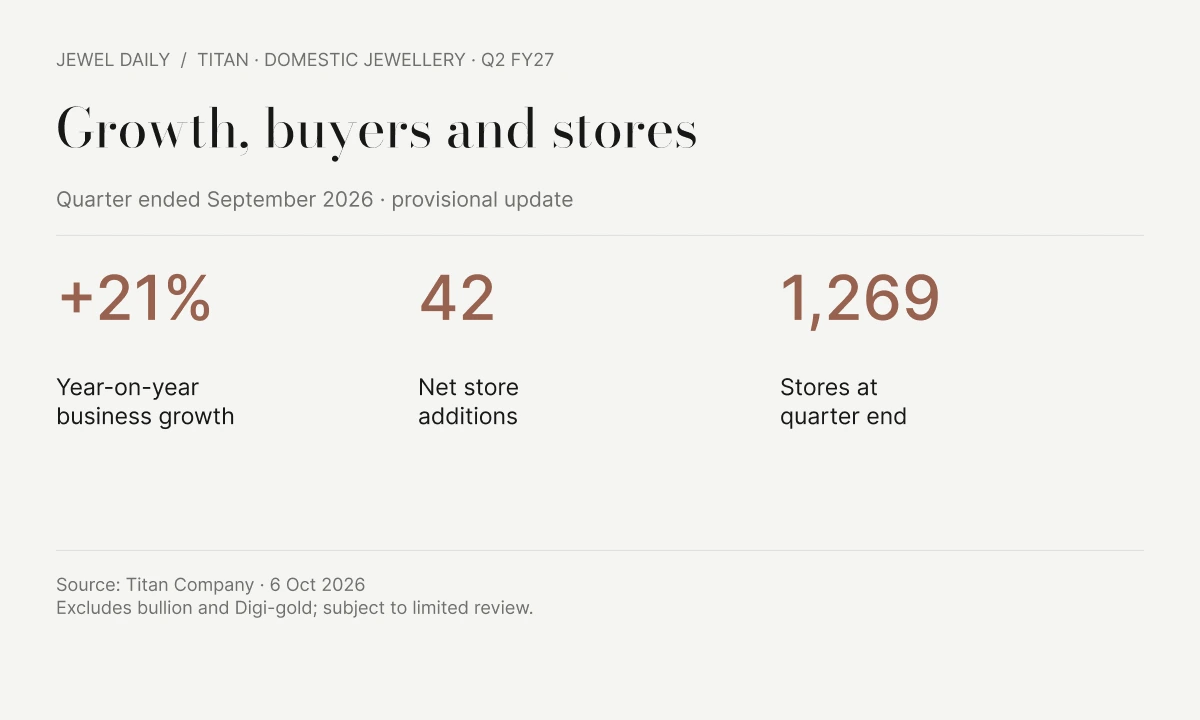
Titan 第二财季国内珠宝业务增长21%,门店增至1269家
Titan 2026—2027财年第二季度更新显示,珠宝业务延续增长。镶嵌珠宝与素金表现不同,数据仍属初步披露。
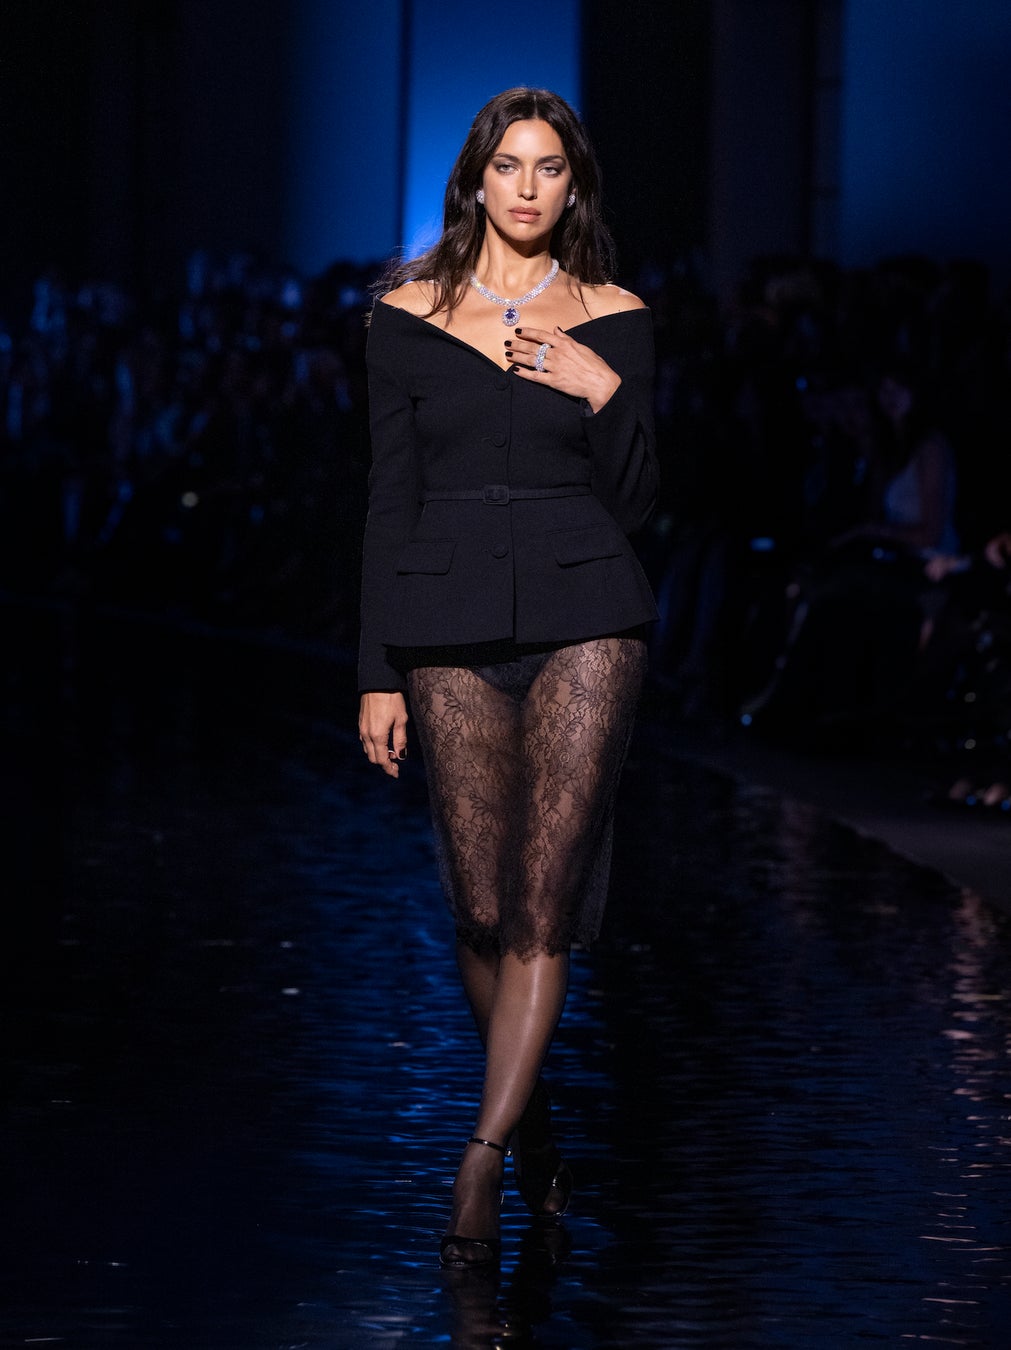
Messika presented its Terres de Contrastes high-jewelry show at the Grand Palais on October 1, drawing the stage palette from three Botswana landscapes. Carine Roitfeld collaborated on styling, Adriana Lima opened, and Irina Shayk closed wearing the Okavango Blue necklace with its 20.46-carat blue diamond.
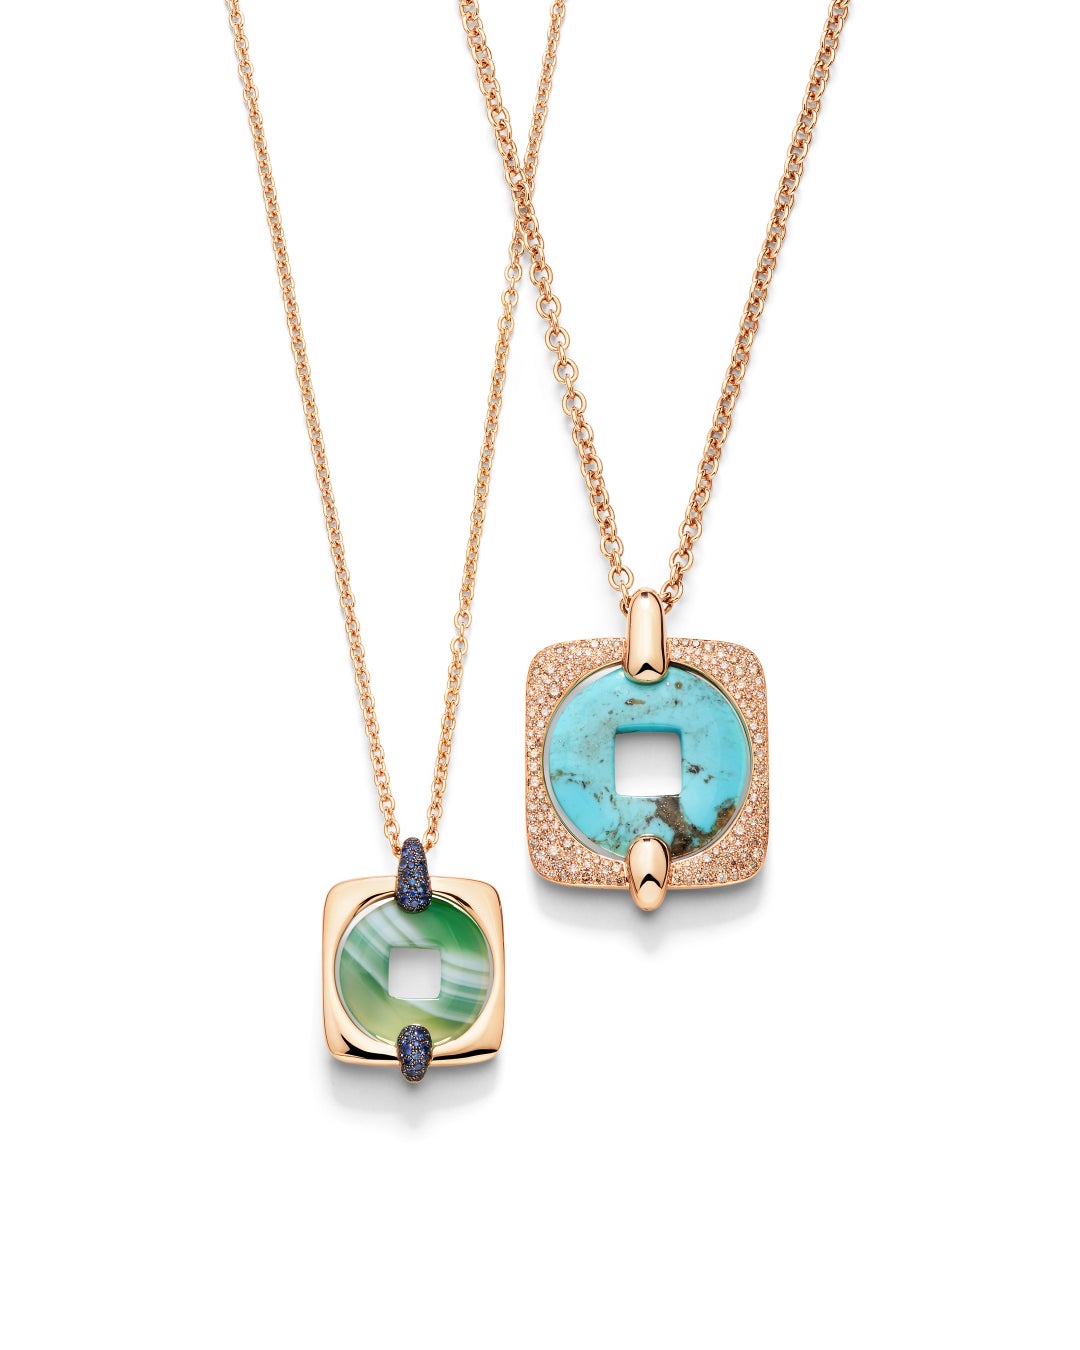
A 1997 pendant inspires a capsule with two sizes and 33 stone-and-pavé combinations.